Start With the Denial Letter
The denial letter should state the reason for the decision and the policy language relied on. That reason determines the best response. A denial based on late notice calls for a different response than one based on wear and tear or an exclusion.
Ask for a copy of your full policy, including endorsements, and any engineer or adjuster reports the insurer used. Our page on denied insurance claims explains the most common denial reasons.
Option 1: Request Reconsideration
If the denial was based on missing information or a factual mistake, you can ask the insurer to reconsider. Send a written request with the evidence that answers the stated reason, such as a contractor's report, photos, or proof of when you reported the loss. Keep copies and note the date sent.
Option 2: Appraisal for Disputes Over Amount
Many policies include an appraisal clause. Appraisal resolves disagreements about how much the loss is worth, not whether it is covered. Each side picks an appraiser, and the appraisers pick an umpire. An award agreed to by two of the three is usually binding on the amount.
Appraisal can be faster than a lawsuit, but each side generally pays its own appraiser and shares the umpire's fee. It is not the right tool when the insurer denies coverage altogether.
Option 3: Mediation Through the State
The Florida Department of Financial Services offers a mediation program for many residential property claim disputes. It is informal and non-binding, and the insurer generally pays the mediation fee. It can be useful when both sides are open to settling.
Option 4: Pre-Suit Notice and Litigation
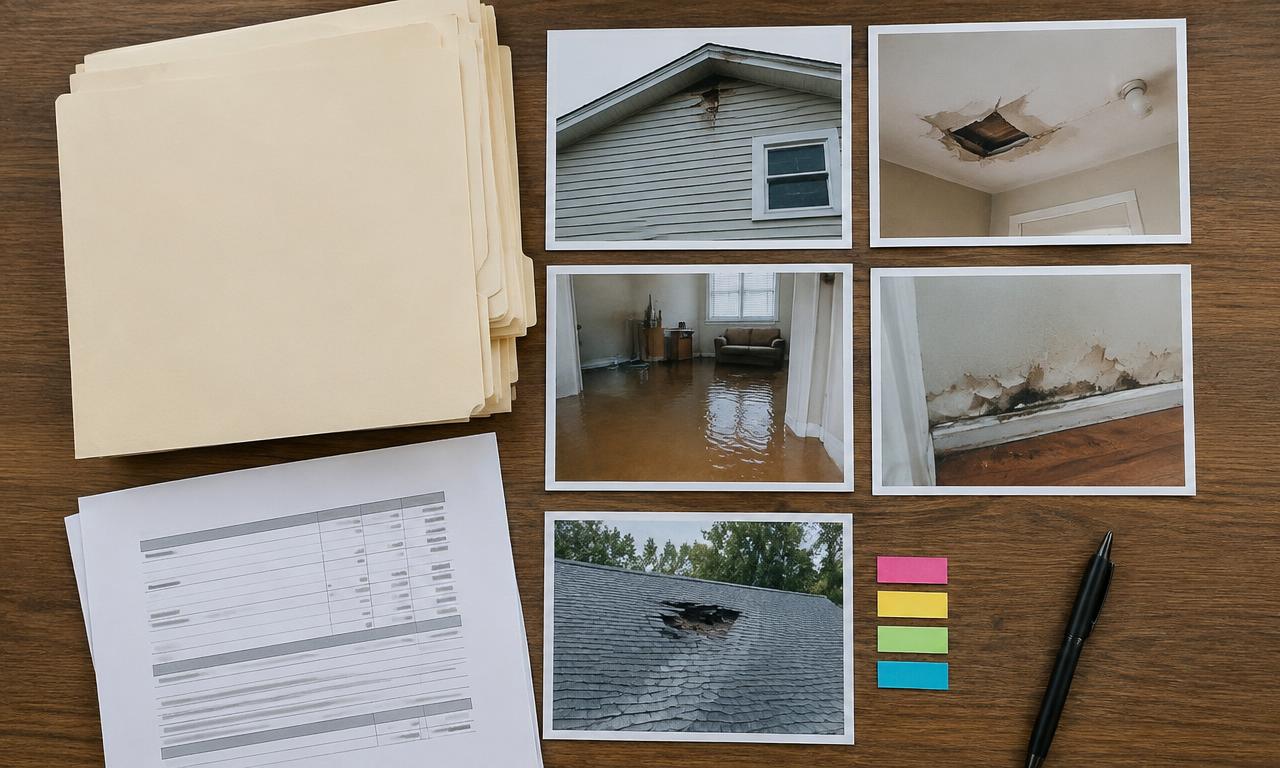
Before filing suit over a residential or commercial property claim, Florida law requires a written notice of intent to initiate litigation, served at least 10 business days before filing, with a presuit settlement demand or disputed amount and supporting estimate. The insurer then has a chance to respond, inspect, or demand appraisal.
A lawsuit over a property insurance claim must generally be filed within one year of the date of loss for policies issued after the 2023 changes, so timing matters. Our resource on the property insurance claim timeline lays out the key dates.
Mistakes That Weaken a Challenge
- Waiting too long and missing a reporting or filing deadline.
- Making repairs that remove evidence before it is documented.
- Responding by phone only instead of in writing.
- Choosing appraisal when the real dispute is coverage.
- Signing a release without understanding what it gives up.
Our guide to common property claim mistakes covers more.
How Orellana Law Can Help
Denial Review
We read the denial, the policy, and the insurer's reports to identify whether the stated reason holds up.
Choosing the Right Path
We explain whether reconsideration, appraisal, mediation, or litigation fits your dispute.
Pre-Suit Strategy
We prepare the required notice and supporting documents so your claim is positioned if it goes to court.
Litigation
If the insurer will not correct its decision, we file suit within the applicable deadline.
Serving all of Florida
Appealing a Denied Claim Guidance in Miami-Dade County and Across Florida
Orellana Law has one office in Miami and serves clients with appealing a denied claim matters throughout Miami-Dade County and across the entire State of Florida. Wherever you are in the state, you can meet with the firm by phone or video. Contact the firm to discuss your situation.